Commercial and semi-commercial property - offices, retail units, mixed-use buildings - sits outside FCA-regulated mortgage rules. We handle these via our specialist commercial desk, with the same honest, numbers-first approach but a different lender universe.
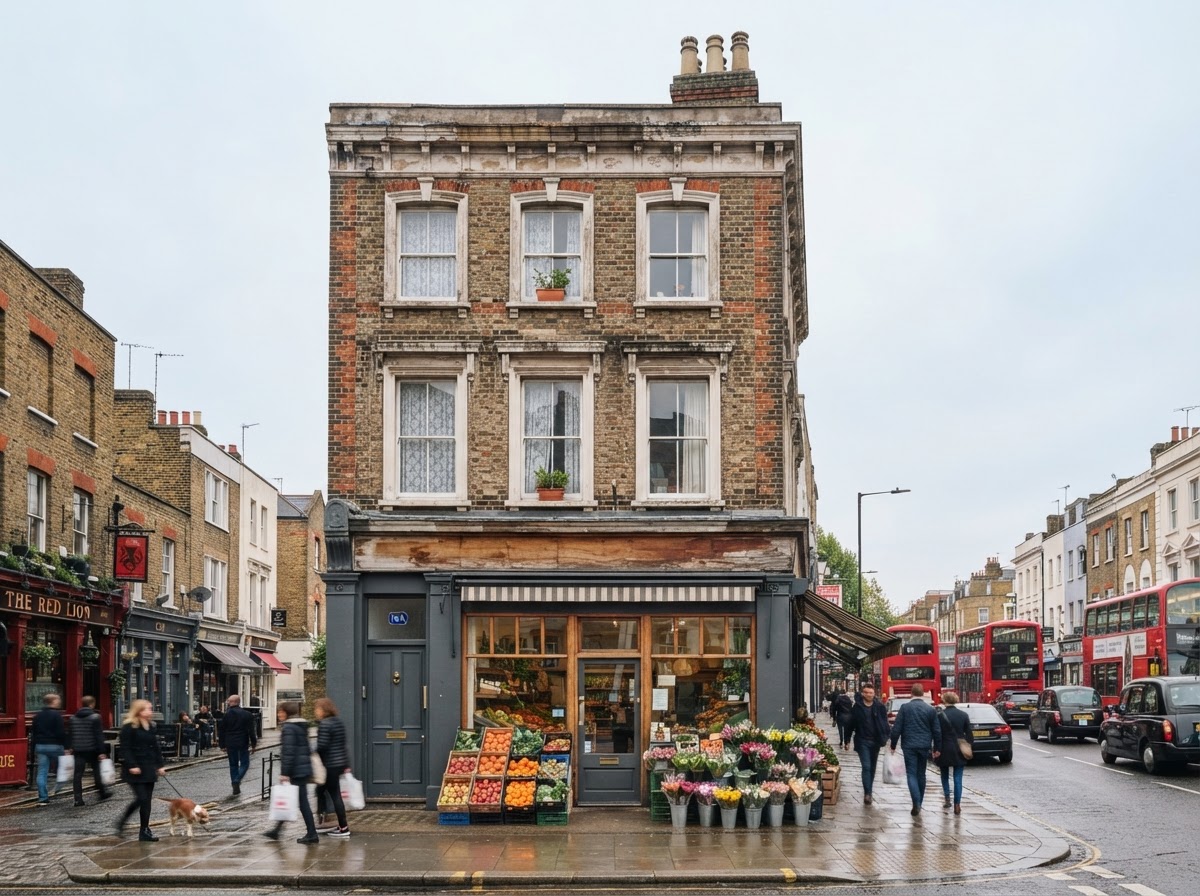
What counts as commercial
Semi-commercial (part residential, part commercial), offices, retail units, warehouses and mixed-use buildings all fall under commercial lending. The lending criteria, rates and terms differ significantly from residential mortgages.
- Semi-commercial and mixed-use buildings
- Offices, retail units and warehouses
- Different lender universe and criteria
How we approach it
Commercial lending is assessed on the property's income and your business profile, not personal affordability. We prepare a clear case and approach specialist commercial lenders, managing expectations on LTV (often 60%–70%) and rates.
- Assessed on property income and business profile
- LTV typically 60%–70%
- Specialist commercial lender panel